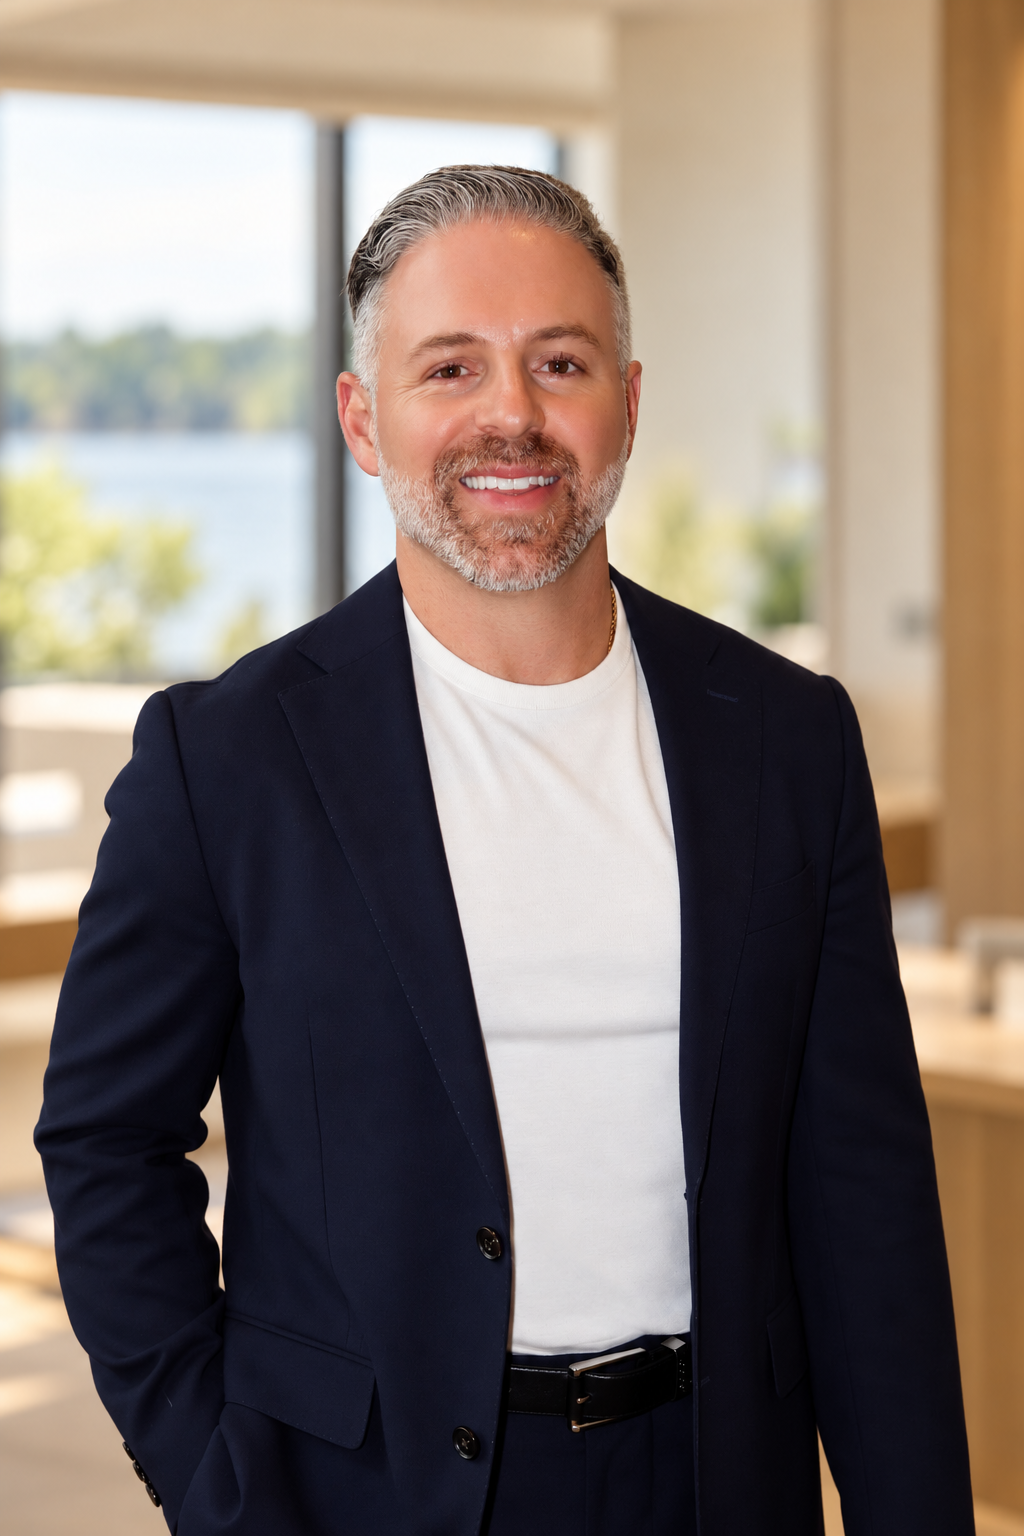
Taylor Foster
Founder & Wealth Advisor
Founder of Altura Wealth, a division of Boria Wealth Management, helping clients connect financial decisions with the lives they want to build.
A clearer picture of your wealth.
More room for the life you want to live.
Personal wealth management for business owners, families, and professionals — from the shores of Lake Minnetonka to wherever life takes you.
Life is bigger than your portfolio.
Your financial plan should be, too.
Welcome to Altura Wealth — a modern, values-driven wealth management firm built around one core belief: money should support a meaningful life, not distract from it.
"In wealth management, you have to understand two things: money and people — not one or the other."
— Taylor Foster, Founder
You work hard for your money. You deserve a clear sense of where it’s taking you. I help individuals, families, and business owners bring purpose and direction to their financial decisions, replacing guesswork with a thoughtful roadmap built around their lives. As the founder of Altura Wealth, my goal is to make advice personal, accessible, and practical—connecting your money, mindset, and the things that give your life meaning.
With nearly two decades of experience, I bring both technical perspective and a personal understanding of the people behind the plan. Wealth management runs in my family: my grandfather began his career as a financial advisor in the 1970s, and the lessons passed down through him, my uncle David Foster, and my mentor George Klima continue to shape my approach. Their influence instilled a lasting respect for trust, sound judgment, and relationships built over time. Those values guide how I serve clients today—with careful listening, clear advice, and a commitment to doing right by the people who place their confidence in me.
Outside the office, I enjoy golfing, hunting, coaching, and cooking, along with training for HYROX competitions. The discipline, consistency, preparation, and resilience I bring to training also shape how I approach long-term financial planning: set a meaningful goal, build a sound plan, and keep showing up.
My greatest joy, though, is time with family—especially my wife and best friend, Mackenzie. Building a life together is the most meaningful part of my own journey, and between us, we’re fortunate to share in the lives of eight nieces and nephews. Those relationships are a daily reminder of the belief at the heart of Altura Wealth: money should support a meaningful life, leaving more room for the people and experiences that matter most.
Meet the Boria Wealth Management team → Founder, Altura Wealth · Wayzata, MN
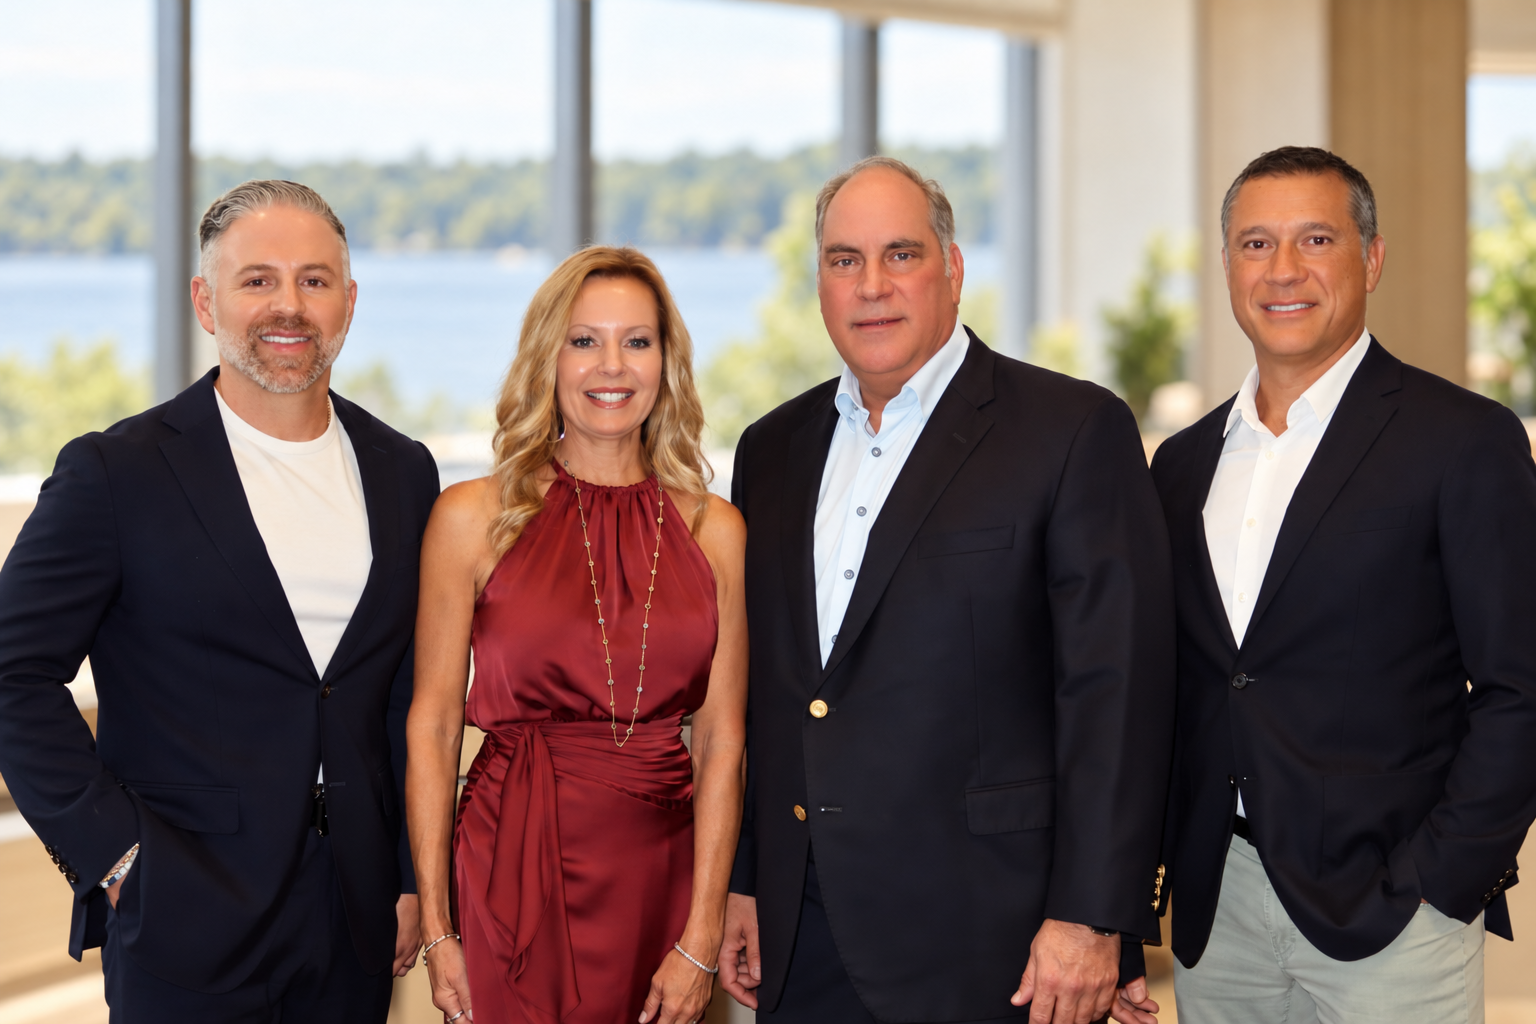
Altura Wealth is a division of Boria Wealth Management. Our team brings together financial advice, office management, and investment research, with a shared focus on the individuals, families, and business owners we serve.
Founder & Wealth Advisor
Founder of Altura Wealth, a division of Boria Wealth Management, helping clients connect financial decisions with the lives they want to build.
Office Manager
Anne oversees office management for Boria Wealth Management, supporting the day-to-day work of the team.
Owner & Lead Advisor
With 30 years in practice, Patrick works with individuals, families, and business owners, sharing Taylor’s personal approach to financial advice and long-term relationships.
Head Research & Market Analyst
Curt leads research and market analysis for Boria Wealth Management, bringing a dedicated research perspective to the team.
Shared perspective. Personal attention.
Wealth built around what matters to you.
One comprehensive fee. One coordinated relationship. Every aspect of your financial life — managed, connected, and aligned with your goals.
Good planning brings order to competing priorities. Our blueprint connects your cash, debt, investments, and family goals—so you can see what to focus on next.
START HERE · BUILD YOUR FOUNDATION
Educational framework, not a prescribed order for every household. Eligibility, contribution limits, tax treatment, and account protections vary. Reserve targets and the 7.5% debt threshold are planning reference points. Insurance and other protection needs are reviewed throughout the process.
An emergency fund and a retirement portfolio have different jobs. We match the investment conversation to when you need the money, how much flexibility you have, and the risk you can bear.
Emergency fund & near-term needs
Prioritize access and stability for money you may need soon. Cash and money market products have different protections and risks.
College, a home & meaningful milestones
Balance growth potential with a mix of assets, revisiting risk as the spending date approaches.
Retirement & generational wealth
Consider growth-oriented investing for distant goals while keeping diversification, volatility, and your ability to stay invested in view.
The right risk starts with the right question:
“When will you need this money?”
Hypothetical allocations adapted from the Altura Wealth Blueprint for educational illustration only. They are not model recommendations, forecasts, or guarantees. All investing involves risk, including loss of principal. Diversification does not ensure a profit or prevent a loss. Your allocation should reflect your individual circumstances.
Connect your goals to a plan ↗One of my goals for every client is to become a world class saver. That starts with a repeatable habit: give your future a place in today’s budget, then put the plan into motion.
“It’s not just what you earn.
It’s what you consistently keep.”
Married couple, both under age 50
$350,000 combined gross annual income
| Where it goes | Annual savings |
|---|---|
| High-yield savingsEmergency reserves & near-term goals | $24,000 |
| Roth IRA strategy*$7,500 per spouse · eligibility & tax review required | $15,000 |
| 401(k) contributions$24,500 per spouse · employee contributions | $49,000 |
| 529 education plansCombined household contribution for the kids | $5,000 |
| Total new annual savings | $93,000 |
$93,000 saved ÷ $350,000 gross income = 26.6% savings rate
We use 20% of gross income as a planning goal to work toward—not a pass-or-fail test. Your starting point and the right target depend on your life.
Build your savings plan ↗01Automate the intention. Direct savings before everyday spending takes over.
02Give each account a job. Connect cash, retirement, and education savings to real goals.
03Grow into the habit. Revisit contributions as income, priorities, and family needs change.
Hypothetical illustration, not an actual client or a recommendation for every household. Savings rate includes new household contributions only; it excludes employer matches, investment returns, transfers, and conversions of existing assets. Monthly amounts are annual totals divided by 12. Assumes each spouse has sufficient eligible compensation and access to a 401(k); no catch-up contributions are included. The $5,000 education allocation is a savings goal, not a 529 contribution limit.
*2026 base limits are $7,500 per person across traditional and Roth IRAs combined and $24,500 per person for 401(k) employee deferrals. Direct Roth IRA contributions phase out at modified adjusted gross income of $242,000–$252,000 for married couples filing jointly. This example does not assume direct Roth eligibility at $350,000 of household income. An advisor and tax professional would evaluate whether an indirect contribution/conversion approach is appropriate, including existing IRA balances and potential taxes. 2026 IRS limits ↗
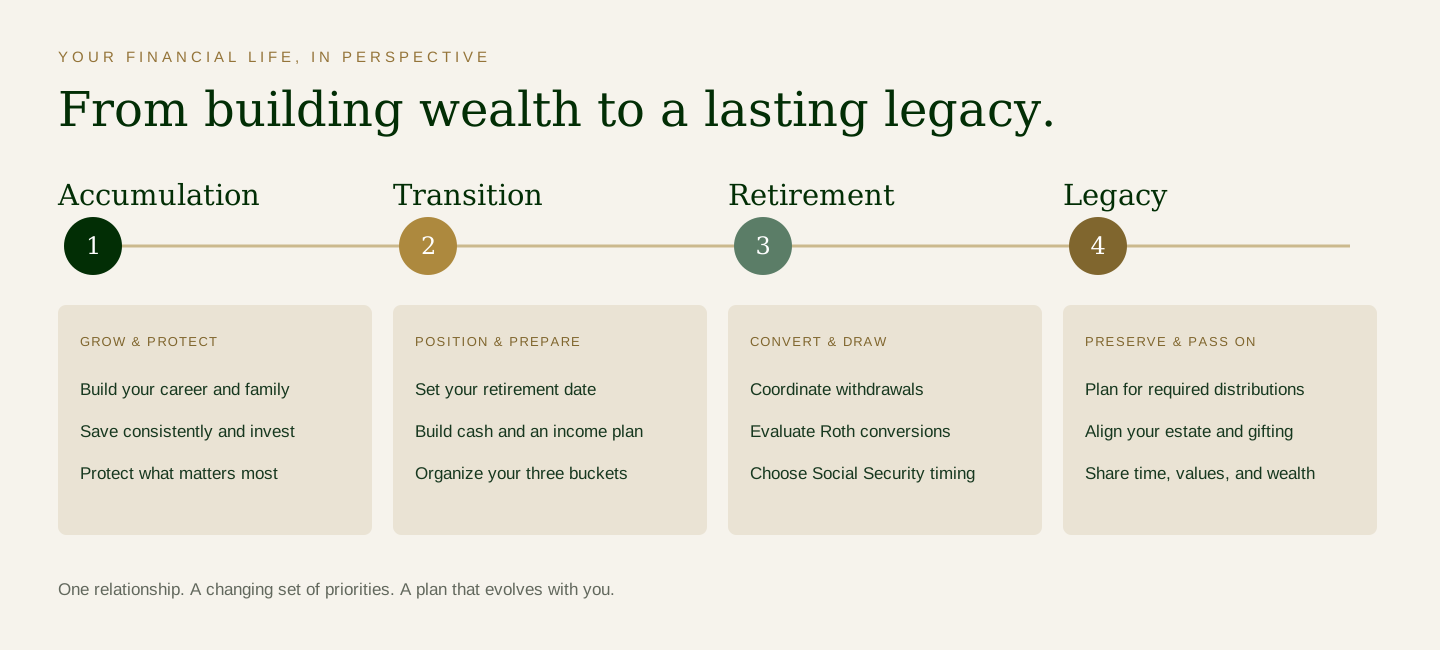
Building wealth is only part of the story. We help connect what you’re working toward today with the freedom, experiences, and legacy you want tomorrow.
 Explore the full roadmap ↗
Where are you today? Choose a phase to explore your priorities.
Grow & protect — with every decision connected to your bigger picture.
Talk about your next chapter ↗Position & prepare — with every decision connected to your bigger picture.
Talk about your next chapter ↗Convert & draw — with every decision connected to your bigger picture.
Talk about your next chapter ↗Preserve & pass on — with every decision connected to your bigger picture.
Talk about your next chapter ↗These phases overlap, and legacy planning can begin at any age. Reserve targets are illustrative and personalized to your needs. Roth conversions can create current income taxes. RMD timing depends on birth year and account rules; the starting age increases to 75 beginning in 2033 under current law. IRS RMD guidance ↗
Give each dollar a purpose. Separate near-term spending from money invested for later, then connect the pieces with a thoughtful withdrawal and refill strategy.
For life right now.
Cash, high-yield savings, and short-term Treasury bills.
Help fund portfolio withdrawals and unexpected expenses, reducing the need to sell longer-term investments during a downturn.
For the years ahead.
A tailored mix that may include high-quality bonds, income-oriented investments, and fundamentally sound growth and value stocks.
Support the next stage of spending and help replenish cash, with risks and costs reviewed for each investment.
For a bigger tomorrow.
Diversified stocks and growth-oriented funds, held in accounts chosen with tax and estate goals in mind.
Seek long-term growth to help address inflation and support future spending, giving, and your legacy.
Growth → Income → Liquidity → Your life
Review. Rebalance. Replenish. Adjust withdrawals and refill decisions to markets, taxes, and your needs.Illustrative time horizons, not fixed allocations or guaranteed income. All investing involves risk, including loss of principal. Bucketing does not eliminate market risk. Account types such as Roth IRAs are distinct from the investments held inside them.
Let’s build your version ↗Choose a topic to request information from Taylor by email.
Featured
Investing
Planning
If you're looking for a trusted advisor who sees money as a tool — one designed to create freedom, protect your family, and elevate your life — we'd love to hear from you.
Investment advisory services offered through Boria Wealth Management, a registered investment adviser. Registration does not imply a certain level of skill or training. All investing involves risk, including the potential loss of principal. Past performance does not guarantee future results. The information on this website is for informational purposes only and should not be construed as investment, tax, or legal advice. Please consult a qualified professional before making any financial decisions.